
Taxes & Structures
When Your Money Is Suddenly "Lazy"
Klaus J. P.-Kilfitt · 31 August 2026 · 9 min read
Europe's savers are sitting on ten trillion euros. The EU wants to "mobilise" this capital – and is currently building the financial and control architecture for doing so, one in which the way out is becoming ever more difficult.
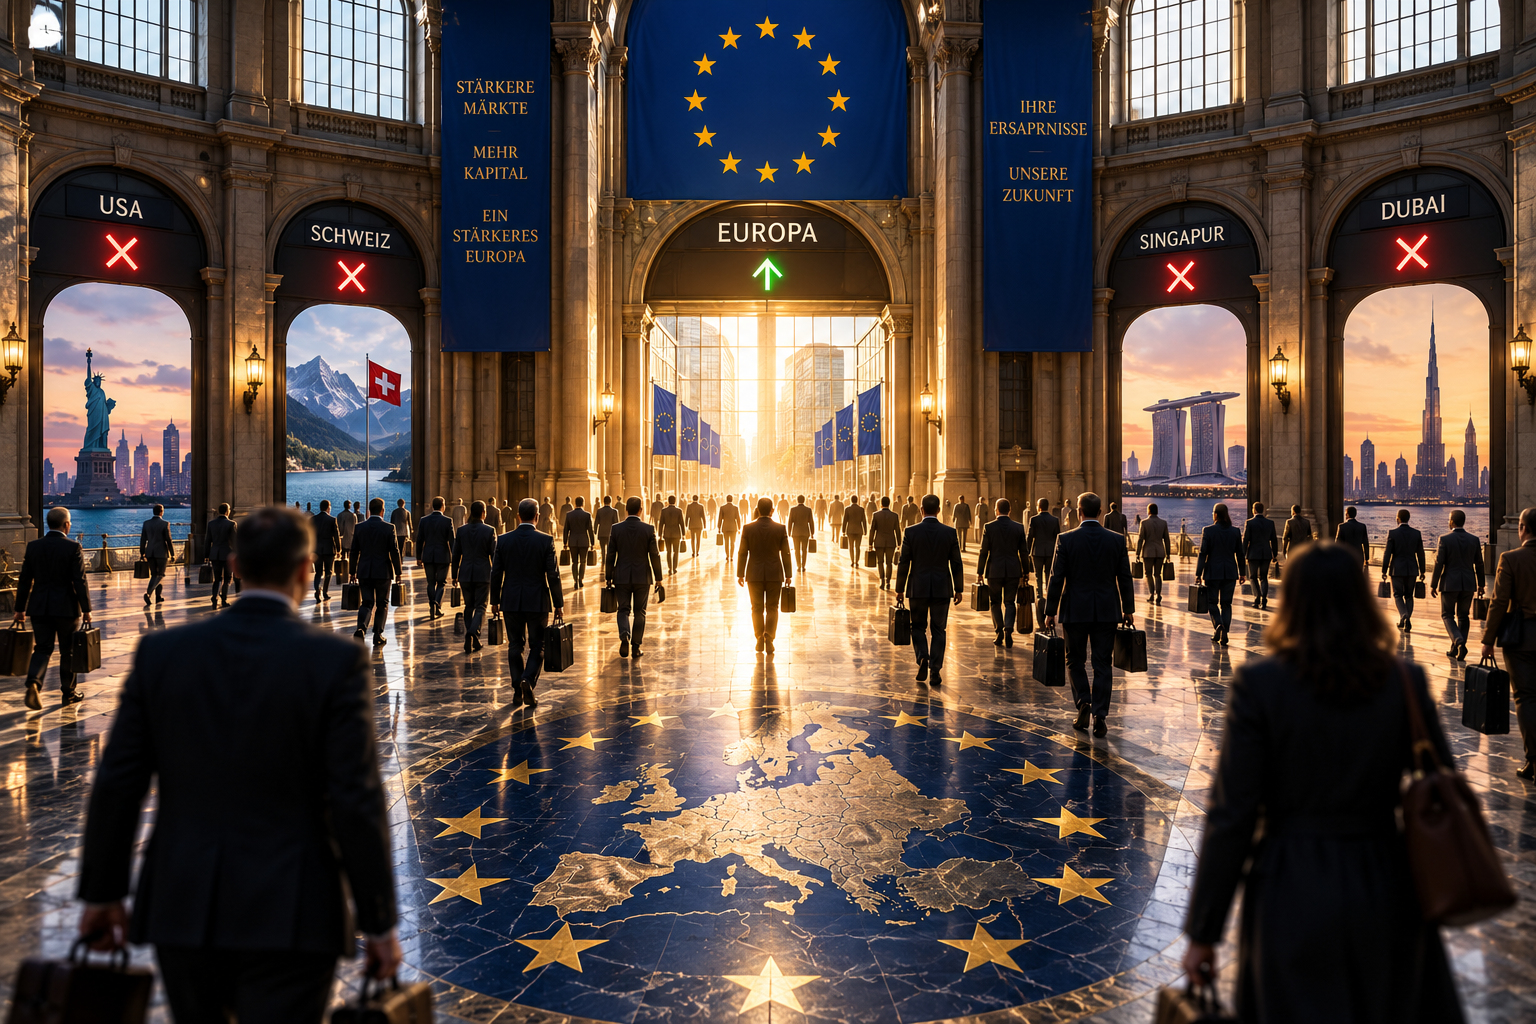
There are political speeches in which a single word reveals more about the underlying thinking than twenty pages of strategy paper. Ursula von der Leyen delivered an exceptionally striking example of this in Paris at the end of August 2026. Europe, the President of the European Commission explained to French entrepreneurs, actually has enough savings to finance its projects. The problem lies elsewhere: "Malheureusement, cette épargne est paresseuse." Unfortunately, these savings are lazy.
One can argue about whether "paresseuse" was a particularly happy choice of word. In the English version it was subsequently rendered a little more gently as "sitting idle", turning lazy money into money that is merely idling on the sofa, so to speak. The substance of the statement, however, does not change as a result. Von der Leyen put a figure on the wealth in question: 10,000 billion euros – ten trillion euros in savings held by European households in bank accounts – and went on to lament that a considerable share of European savings is, moreover, invested outside Europe. Then came the sentence that really matters: Europe must now put this money to work for its own projects and companies.
That is, to begin with, not a conspiracy theory but a stated political objective, from the mouth of the Commission President herself.
Taken on its own, such a statement may not seem especially spectacular, let alone threatening. But as we recently explored in our article series 'Every Wall Is Built of Individual Bricks' and 'The Glass Citizen Doesn't Need a Wealth Register', the full picture only emerges once you stop looking at individual measures in isolation.
Ten trillion euros, apparently in the wrong place
That Europe has a financing problem is not something Ursula von der Leyen invented. European companies rely more heavily on bank financing than their American competitors, capital markets are more fragmented, and a great deal of European capital flows into the United States or other attractive markets – into real estate or into companies which, thanks to far better underlying conditions, offer growth and return potential quite different from that of European projects suffocated by requirements and bureaucracy. The EU has therefore been trying for years to create larger, more integrated European capital markets. Today's Savings and Investments Union is, in that sense, not an idea conjured out of thin air.
Nor is the figure of 470 billion euros entirely new. Von der Leyen had already cited this order of magnitude for additional investment potential from completing the Capital Markets Union in her 2024 political guidelines.
One can find all of this economically reasonable. One can even take the view that someone who leaves large parts of their wealth sitting unremunerated in a current account for decades is not exactly pursuing a brilliant investment strategy.
But that is not really the question.
The question, rather, is since when it has been the task of a political institution to judge whether its citizens' savings behaviour is productive enough – and, above all, what happens when those citizens reach a different assessment, or simply pursue different goals.
Because a bank balance is not "lazy". It is liquid. It can be a safety buffer, an entrepreneurial reserve, purchasing power for a future investment, or simply the result of its owner's decision to do nothing with it at all, for now. The state may consider this decision economically suboptimal – but for the owner, that does not make it wrong.
This is where a fundamental shift in perspective begins: a citizen's wealth is no longer regarded solely as their private property, but simultaneously as an as-yet insufficiently used resource for achieving economic-policy objectives.
And ten trillion euros is a damn large resource.
"Mobilise" sounds nicer than "compel"
The political vocabulary for such processes is remarkably friendly. Capital is to be "mobilised", savings "activated", investment "unlocked". No one speaks of telling people what to do with their money.
At present, that would also be factually wrong.
There is no decision requiring European savers to invest their bank balances in European companies, government bonds, infrastructure projects or defence companies in future. Nor is there any decision on a European wealth levy on bank assets.
But it makes sense to judge political developments before the last implementing regulation has been published in the Official Journal. Anyone assessing risk – whether of a company, a state, or their own wealth – deals in scenarios and probabilities. They look at incentives, institutional developments, instruments already created and the declared political direction, and then ask what development can plausibly emerge from all of that.
That is precisely why it is worth reading von der Leyen's speech not in isolation, but together with other developments of recent years.
While wealth is meant to be activated, the way out keeps narrowing
With CRD VI the European Union has created a rule that, from 11 January 2027, will substantially restrict cross-border access to certain banking services provided by institutions in third countries. Banks outside the EU that want to conduct deposit-taking, lending or guarantee business with customers inside the Union will, in principle, need a suitably licensed establishment in the relevant member state. The few remaining exceptions, such as reverse solicitation, turn out in practice to be little more than a fig leaf, and do little to change the ever-higher hurdles one must clear to remain master of one's own investment decisions.
The claim currently circulating online – "EU citizens will no longer be allowed to open accounts abroad from 2027" – is admittedly a simplification, since the law does not prohibit citizens from holding a foreign account; it regulates the third-country bank and its access to the European customer. In practice, though, the result is much the same.
If a bank in Singapore, Switzerland or another third country can no longer, for regulatory reasons, simply serve a customer resident in Germany, it ultimately makes little difference to that customer whether the rejection letter reads: "You are not permitted to open an account with us" or "We are not permitted to offer this service in your circumstances."
The legal hook may be different – but in neither case does he end up with an account.
And this is where the timing becomes interesting: on one side, the EU's political leadership declares that European savings are, to a large extent, sitting unproductively in accounts or being invested outside Europe, and must be made to serve European interests more strongly. On the other side, alongside many further instruments of control, a regulatory framework is emerging that makes certain banking relationships between EU residents and third-country institutions more difficult.
Does this prove that CRD VI was adopted in order to lock the ten trillion euros inside Europe?
Taken in isolation, no.
Is it sensible to consider both developments together when assessing the long-term direction of European financial policy?
Absolutely.
Residence becomes the financial switch
We have already described elsewhere just how paradoxical this development can become. Anyone leaving Germany may well find that their German bank suddenly no longer wants them, even though neither their creditworthiness nor their wealth nor their decades-long business relationship has changed. Only a single piece of information in the customer file has changed: their place of residence.
Anyone who stays in Germany, by contrast, may in future find that certain banking relationships outside the European Union become more difficult.
That is not a contradiction. It is the same development, merely viewed from different sides.
Residence is becoming an ever stronger regulatory anchor point, determining which financial services a person may use, which bank is allowed or willing to serve them, and under what conditions wealth may be structured across borders. Add to this AML rules, automatic exchange of information, various beneficial-ownership registers, reporting obligations and an increasingly centralised European supervisory apparatus.
None of these measures, taken alone, is the famous wall.
That is, however, rather cold comfort if the individual bricks eventually add up to one anyway.
No one needs a secret master plan for this
This is perhaps the biggest fallacy in the public debate. Anyone who points to a long-term trend of tightening regulation is routinely told that there is no proof of a secret plan culminating in capital controls, wealth levies or other interventions.
Of course there is no such proof. Perhaps there is not even such a plan.
None is needed.
Political systems do not evolve exclusively according to a script written twenty years earlier. Institutions react – depending on political majorities – to budget problems, crises, wars, demographic shifts and financing gaps that grow alarmingly or emerge anew. What matters, therefore, is not so much whether Ursula von der Leyen has a wealth levy for 2028 sitting in her desk drawer today. What matters is what infrastructure has been built by then, and what interventions that infrastructure makes possible if the need arises.
Anyone who wants to tax wealth needs to know where it is.
Anyone who wants to control capital movements needs regulated interfaces.
Anyone who wants to steer investment decisions needs incentives, rules and, where necessary, disadvantages for alternatives artificially created through conditions and access restrictions.
Anyone who wants to integrate a financial space more tightly needs centralised supervision.
And anyone who wants to stop capital escaping such measures will, sooner or later, inevitably have to think about how open the doors to the outside should remain.
Once again: none of this means every one of these steps will happen. It merely means that each building block already in place makes certain scenarios easier to implement than before.
For a sound risk analysis, that is entirely sufficient.
History does not repeat itself – but it rhymes
The idea of drawing on private wealth in extraordinary fiscal situations would, in any case, be no historical novelty in Europe. Germany has its war bonds, currency reforms, wealth levies and the postwar Lastenausgleich (equalisation-of-burdens levy). Other European states have had their own experiences with special levies, capital controls, forced conversions or other extraordinary interventions in private wealth.
That does not mean 1922 or 1952 will repeat itself in 2029. History is not an endless loop. But anyone who studies it cannot help but notice that the boundary of what is politically conceivable and feasible is considerably more flexible than it appears in calm times.
Precisely for that reason, the objection "there are no such plans today" is of limited value for long-term wealth decisions. Anyone structuring their wealth for the next twenty or thirty years is not only interested in what a government intends today. They are interested in what risks can arise within that period, and how dependent they wish to be on those risks not materialising.
Diversification begins before the crisis
None of this implies that everyone should empty their German bank account, bury gold bars in the garden and head off tomorrow to a law firm in Panama. Anyone who, out of fear of a hypothetical future risk, makes rash and poor decisions has gained nothing.
The sensible response is diversification.
And not merely the kind of diversification banks usually mean when they sell a client five different securities that then all sit in the same custody account, at the same bank, under the same jurisdiction and within the same regulatory system.
International wealth diversification can encompass different banks, currencies, jurisdictions, asset classes, storage locations, corporate structures and – for those for whom it fits their life plans – different residence and domicile options as well.
Not every one of these options makes sense for everyone. Some involve costs, others tax obligations, yet others regulatory effort. But options have a value that often only becomes apparent once you need them.
And some options cannot be conjured up on short notice.
A foreign bank account that a bank is no longer permitted or willing to open cannot be set up retroactively. A right of residence does not materialise just because you declare at the airport that you urgently need one. An international corporate structure is best not founded on a Friday afternoon, after capital controls have been announced for the following Monday.
Resilience is built before the crisis. Just as the immune system must be strengthened before illness confines you to bed.
Perhaps "paresseuse" was the right word after all
Seen in this light, von der Leyen's choice of words was probably unintentionally honest and revealing. It lays bare the fact that owners and policymakers view the same wealth from entirely different angles and with entirely different intentions.
For the owner, 100,000 euros in an account may be a reserve, a piece of independence, or simply capital whose use they wish to decide on later. For European economic policy, ten trillion euros of such balances is an enormous source of financing that has so far not been sufficiently "mobilised".
Owners should, above all, recognise that this other view of their property exists, and what consequences may follow for them from that different way of looking at things.
Because alongside this political vision, a surveillance architecture is emerging in which wealth and financial flows become ever more transparent, financial services come under stronger centralised supervision, and certain cross-border options become regulatorily more demanding. Whether this will, in a few years, produce nothing more than a more efficient European capital market, or eventually a system in which the individual's freedom over their own wealth is substantially more constrained, no one can seriously predict today.
One can, however, assess probabilities.
And anyone who considers the direction wrong need not wait until a probability has hardened into certainty.
Sources & further data
- European Commission – Speech by President von der Leyen (Paris, August 2026) — Official audiovisual material and speech transcript from the European Commission's address to French entrepreneurs.
- European Commission – Savings and Investments Union — Official presentation of the Savings and Investments Union, its aims and measures.
- Directive (EU) 2024/1619 (CRD VI) — Amending directive to the Capital Requirements Directive, in particular Art. 21c on the third-country branch regime and its associated transitional provisions.
- European Commission – Political Guidelines 2024–2029 — The Commission President's programmatic guidelines, including the order of magnitude of additional investment potential from completing the Capital Markets Union.
- German Federal Ministry of Justice – Lastenausgleichsgesetz — The text of the German equalisation-of-burdens law, cited as a historical reference case of state intervention in private wealth.
More perspectives
Banking & Finance
Wenn der Wohnsitz über das Auslandskonto entscheidet
Sie leben in der EU und führen ein Konto bei einer Bank in der Schweiz, den USA oder einem anderen Drittstaat? Mit CRD VI ändern sich die Spielregeln – und betroffen sein kann auch das ganz normale Girokonto.
Read articleBanking & Finance
Ihre Bank kündigt Ihnen nicht, weil Sie auswandern
Ein Auslandswohnsitz ist für eine deutsche Bank nicht grundsätzlich ein Problem. Doch er verändert Aufwand, Risikoprofil und wirtschaftliche Kalkulation. Wer seine Bank- und Depotstruktur erst nach dem Wegzug überprüft, hat möglicherweise genau dann weniger Optionen, wenn er sie am dringendsten braucht.
Read articleFreedom & Society
Für den gläsernen Bürger braucht es kein Vermögensregister
Während über ein europäisches Vermögensregister diskutiert wird, entsteht längst eine viel wirkungsvollere, dezentrale Infrastruktur. Automatischer Informationsaustausch unterschiedlichster Register weltweit, eine eindeutige digitale Identität und KI-gestützte Vernetzung haben den gleichen Effekt – ganz ohne zentrale Datenbank.
Read article