
Taxes & Structures
Out of the Frying Pan: Exit Taxation in International Comparison
Klaus J. P.-Kilfitt · 20 July 2026 · 9 min read
Anyone leaving Germany usually spends a great deal of time on the question of what tax consequences the departure will trigger. That is sensible – but only half the picture.
Because anyone relocating the centre of their life to another country should not only know how expensive saying goodbye to Germany can be. At least as interesting is the question of what happens when, at some point, they want to leave the new country again.
Otherwise, what looks like a tax liberation can quickly turn into the proverbial leap out of the frying pan and into the fire.
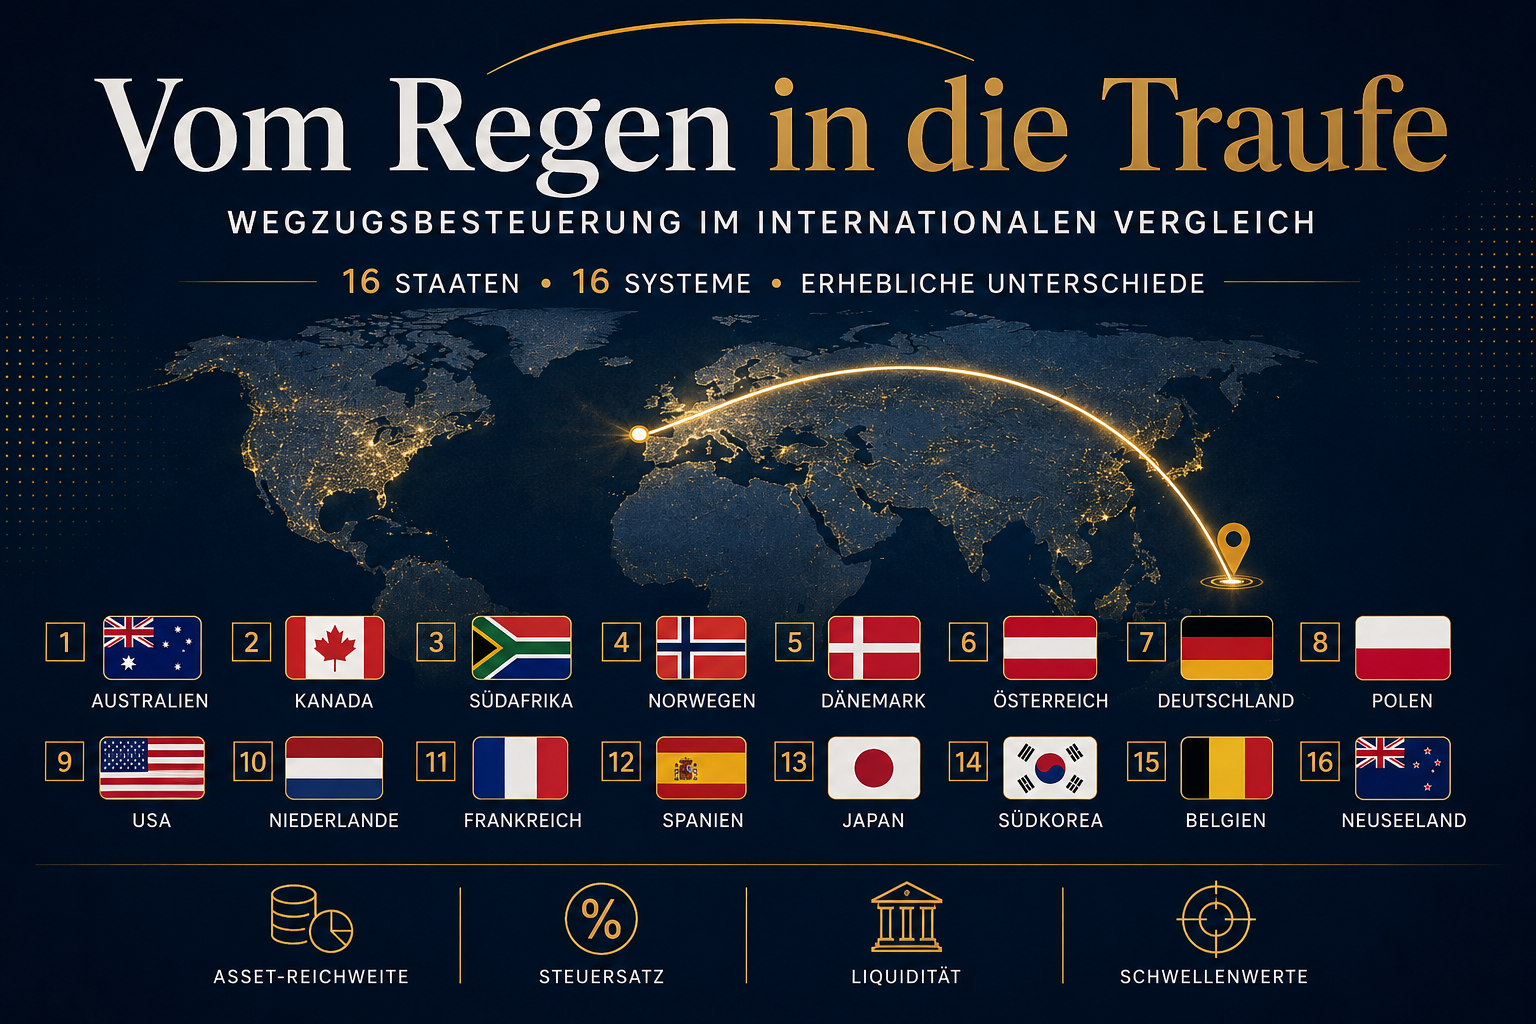
Germany is among the countries that can tax certain increases in value even though they have not actually been realised at the time of departure. So-called exit taxation treats certain hidden reserves, put simply, as though they had been realised upon leaving the country.
This can trigger substantial tax claims – without the person concerned having received any corresponding liquidity from an actual sale.
However, Germany is by no means alone internationally in applying this principle.
A comparative look shows, rather, that a manageable number of countries have general or specific forms of an exit tax, or comparable final tax settlements, for private individuals.
But the differences are enormous.
An Exit Tax Is Not Just an Exit Tax
A mere comparison of nominal tax rates falls short.
What matters first is which assets are covered at all.
Some countries cast a very wide net, capturing almost the entire relevant capital wealth. Others confine their exit taxation to substantial shareholdings in companies or specific financial investments.
Thresholds are equally important.
While some systems already apply to relatively modest wealth, others require substantial shareholding ratios, wealth in the millions, or a long period of prior tax residence.
And ultimately, it is the liquidity effect that determines how painful exit taxation actually turns out to be.
Must the tax be paid immediately? Can it be deferred? Is payment by instalments possible? Or does a tax claim initially arise merely on paper, only falling due upon a later, actual disposal?
A ranking therefore needs a comprehensible evaluation standard.
Our comparison incorporates four factors:
- 40% Asset Scope How wide is the circle of assets covered?
- 25% Effective Maximum Tax Rate How high can the actual burden on the notional gain turn out to be?
- 20% Liquidity Burden on Departure Must payment be made immediately, or are there deferral or instalment arrangements?
- 15% Thresholds, Exceptions and Relief Options How quickly does the system apply, and what possibilities exist to limit its consequences?
1. Australia
Australia has one of the most comprehensive systems in the comparison.
When Australian tax residence ends, in principle all CGT assets are captured that do not continue to qualify as "taxable Australian property" subject to Australian taxation. This can include shares, company interests, funds, cryptocurrencies and other capital investments.
Australian real estate, by contrast, typically remains within Australia's taxing rights and is therefore not deemed to be disposed of.
Taxation is generally at the personal income tax rate, which including the Medicare Levy can currently reach around 47 percent. The Australian CGT discount may apply, where relevant.
However, there is an important election available: exit taxation can be deferred for the assets concerned. They then remain within the Australian tax net until a later, actual disposal.
2. Canada
Canada, too, works with a very broad assessment base.
On departure, a deemed disposal at market value applies to numerous worldwide assets. These include, among others, shares, funds, holdings, art, jewellery and collections.
Exceptions apply in particular to Canadian real estate, certain pension and retirement entitlements, and certain persons who have only recently taken up residence.
It is not the entire asset that is taxed, but the hidden gain contained within it.
For private individuals, depending on the province, this often results in a maximum effective burden of roughly 24 to 27 percent on that gain. Payment can, upon application, be deferred interest-free until the actual disposal.
3. South Africa
On termination of South African tax residence, a deemed disposal likewise generally applies to most worldwide assets.
Exceptions include, among others, South African real estate, certain retirement entitlements and many personal effects.
For private individuals, at most 40 percent of the capital gain is included in taxable income. At a top income tax rate of 45 percent, this results in a maximum effective CGT burden of around 18 percent.
South Africa thus combines a broad assessment base with a lower effective top tax rate than Australia or Canada.
4. Norway
Norway captures in particular shares, company interests, partnership holdings, investment funds, certain investment accounts and financial instruments.
There is, by contrast, no general exit tax on real estate, cash or ordinary personal assets.
The effective tax rate on share gains stands at roughly 38 percent for 2025/2026.
Following the tightening of the rules since March 2024, the tax must generally be paid no later than within twelve years. It is thus not necessarily due in full immediately upon departure.
Furthermore, only increases in value that arose during Norwegian tax residence are taxed.
5. Denmark
Denmark applies its rules to shares and similar securities from a total market value of as little as DKK 100,000.
The general prerequisite is a period of tax liability of at least seven years within the past ten years.
In addition, crypto assets may also be deemed disposed of at market value on departure.
Gains on shares are taxed progressively at around 27 or 42 percent respectively. For shares, a deferral of payment until the actual disposal is possible, though dividends and certain withdrawals partially reduce the deferral account.
6. Austria
Austria generally captures capital assets still within its taxing rights, including free-float shares, substantial shareholdings, funds, bonds and, regularly, cryptocurrencies as well, as soon as Austria loses its taxing right as a result of the departure.
The standard rate is predominantly 27.5 percent, and 25 percent for certain capital investments.
On departure to an EU or EEA state, assessment or payment can, upon application, be deferred until the actual disposal.
In terms of the assets captured, the Austrian system is thus even broader than the German one.
7. Germany
Germany's classic exit tax applies to shares in corporations where, at any point within the past five years, a shareholding of at least one percent was held, and the taxpayer was subject to unlimited tax liability for at least seven of the past twelve years.
Since 1 January 2025, certain investment fund units are additionally captured – in particular where there is a holding of at least one percent in the fund, or acquisition costs of at least €500,000 per investment fund.
For shares in corporations, the effective burden, owing to the partial-income method (Teileinkünfteverfahren), typically stands at around 28.5 percent excluding church tax. For investment funds, the burden depends on the type of fund and the partial exemption applicable.
Payment can generally be made in seven annual instalments, regularly against the provision of security.
8. Poland
For natural persons, Poland captures in particular assets in respect of which the country loses its taxing right as a result of the change of residence. This is chiefly relevant for business and financial assets.
The threshold for application generally stands at a market value of PLN four million.
The tax rate is normally 19 percent, or three percent in certain cases where no ascertainable tax value exists. Under certain conditions, payment by instalments over up to five years is possible.
The compatibility with EU law of certain provisions on the immediate taxation of natural persons is currently the subject of proceedings before the CJEU.
9. The United States
The United States is a special case.
A mere change of residence does not, there, trigger any ordinary exit tax.
Rather, the so-called expatriation tax becomes relevant on relinquishment of US citizenship or termination of long-term green card status – and even then only for so-called "covered expatriates".
Among the decisive factors are wealth and tax thresholds, as well as proper tax compliance over the preceding five years.
In principle, mark-to-market taxation applies to worldwide assets, though with an annually indexed exemption amount applied to the notional net gain.
Ordinary visa holders are not subject to any corresponding exit tax.
10. The Netherlands
The Netherlands focuses in particular on substantial shareholdings of five percent or more.
In addition, Dutch pension, annuity and certain home-ownership products can be affected by a conservatory tax assessment.
The Box 2 tax stands, for 2026, progressively at approximately 24.5 or 31 percent.
The tax on substantial shareholdings is regularly assessed initially and then deferred. It can later fall due in particular on sale, distributions, or certain abusive arrangements.
11. France
France sets comparatively high entry thresholds.
The taxpayer must generally have been resident in France for at least six of the past ten years and hold shareholdings worth at least €800,000 in total, or at least 50 percent, in a company.
Captured are, in particular, shares and company interests, as well as certain deferred capital gains.
The standard burden usually stands at 30 percent including social contributions.
On departure to EU/EEA states, as well as certain cooperative third countries, an automatic deferral of payment applies. Under certain conditions, the tax can even lapse after two or five years respectively, provided the securities continue to be held.
12. Spain
Spain, too, works with high thresholds.
The general prerequisite is tax residence during at least ten of the past 15 years.
Captured are shares and shareholdings where their total value exceeds €4 million, or where a shareholding of at least 25 percent in a company exists and that shareholding is worth more than €1 million.
The notional gain is subject to the Spanish savings tax scale, currently roughly 19 to 30 percent.
On a move within the EU or EEA, there is generally no immediate payment; instead, certain events occurring within a monitoring period can trigger subsequent taxation.
13. Japan
Japan captures certain financial investments and derivatives from a total value of at least ¥100 million.
The general prerequisite is five years of Japanese residence within the past ten years, with certain visa and residence periods treated differently.
Affected are, among others, shares, fund units, bonds and derivatives – but not, typically, cash or real estate.
For securities, the burden including local components often stands at around 20 percent. A deferral over generally five, and in certain circumstances ten, years is possible against the provision of security.
14. South Korea
South Korea's exit tax applies in particular to certain major shareholders following a longer period of tax residence.
Historically, the focus has been on shareholdings in Korean companies. The asset base captured is thus considerably narrower than, for example, in Canada or Australia.
The burden, depending on the shareholding, the company and the holding period, regularly stands at around 22 percent including local tax.
An extension to foreign shares is planned, or has been under discussion, for the coming years.
15. Belgium
Belgium finds itself, in 2026, in a period of tax transition.
A new tax on private capital gains on certain financial investments generally provides for a base rate of ten percent. However, the state of the legislation, as well as individual transitional, exemption and deferral rules, has been altered repeatedly.
The exit tax mechanism attaches to latent gains falling within the scope of the new system. For departures within the EU and EEA, deferral mechanisms are provided.
Since, in principle, only increases in value arising since the introduction of the new system are affected, the burden turns out to be more moderate by international comparison, despite a comparatively broad definition of financial assets.
16. New Zealand
New Zealand marks the other end of our comparison.
There is no general exit tax on worldwide private assets there, nor a comprehensive general capital gains tax.
At the end of tax residence, however, special final settlements can apply – in particular for certain foreign investment fund interests, as well as financing and foreign currency arrangements.
For certain FIF interests, a disposal at market value can be deemed to occur.
This is a narrowly confined technical rule and hardly comparable to the comprehensive systems of Australia or Canada.
Germany Only in Seventh Place? The Reckoning Need Not End There
Seventh place sounds, at first, almost reassuring. However, this ranking deliberately looks only at exit taxation in the narrower sense – that is, a possible one-off tax effect connected with departure.
That does not, however, mean that the tax past in Germany is necessarily concluded.
Because alongside immediate consequences of departure such as exit taxation, the withdrawal of assets from German taxing rights (Entstrickung), or the relocation of functions, German tax law also has instruments that can still take effect years after departure.
One example is extended limited tax liability under section 2 of the Foreign Tax Act (AStG). Under certain conditions, Germany can, in the case of departure to a low-tax jurisdiction, still access certain income for up to ten years.
Another example is the so-called overriding taxation (überdachende Besteuerung) in relation to Switzerland. It can result in Germany retaining certain taxing rights for a transitional period even after a change of residence to Switzerland.
Neither of these belongs, methodologically, in a ranking of exit taxation. They belong in the category of trailing taxation – a dimension that is surprisingly often overlooked in international comparisons of departure.
To put it more pointedly:
"Anyone who, on departure, has already made the acquaintance of exit tax, Entstrickung or the relocation of functions should not automatically assume that the German tax authorities are done with them."
It is precisely the combination of one-off consequences of departure and taxing rights that then continue to apply for years afterwards that can be decisive for the choice of destination country.
Do Not Only Look at the Front Door
Anyone choosing a new place of residence understandably concerns themselves, first, with its advantages.
How high are income and capital gains taxes? Is there territorial taxation? How are businesses treated? What residence rights exist?
These are all important questions.
But a long-term international strategy should contain one more:
How do I get out again one day?
A country can be extremely attractive, from a tax perspective, for moving in, while at the same time having rules that make a later departure considerably more expensive.
Conversely, a country that at first glance appears to tax more heavily can, owing to high thresholds, narrow asset definitions or generous deferral options, prove less problematic on a later departure.
For that reason, the choice of a residence should never be based solely on the present tax burden.
Tax systems change. Personal circumstances change. Businesses are sold, families move on, and political and economic conditions shift.
International freedom therefore does not merely mean being able to leave.
It also means not needlessly tying oneself down again at the next place.
And sometimes it is already decided, at the point of choosing the destination country, whether a departure actually results in more freedom – or merely the next tax cage.
More perspectives
Taxes & Structures
Territorialbesteuerung: Gesetz vs. Praxis – Die gefährliche Lücke
Territorialbesteuerung klingt einfach: Besteuert wird nur, was im Land erwirtschaftet wird. Doch entscheidend ist, wo eine Einkommensquelle steuerlich tatsächlich entsteht. Wohnsitz, Leistungsort, Wertschöpfung und Nachweise können aus einer vermeintlich einfachen Lösung schnell ein steuerliches Risiko machen.
Read articleTaxes & Structures
Steuersysteme der Welt: Was jeder Auswanderer verstehen muss
Steuern folgen dem Wohnsitz. Das gilt in Deutschland – aber nicht überall nach denselben Regeln. Wer auswandert, ohne zu verstehen, nach welchem System das Zielland sein Einkommen besteuert, riskiert unangenehme Überraschungen: Steuernachforderungen, Doppelbesteuerung oder ein Setup, das auf dem Papier clever wirkt, in der Praxis aber nicht funktioniert.
Read articleBanking & Finance
Ihre Bank kündigt Ihnen nicht, weil Sie auswandern
Ein Auslandswohnsitz ist für eine deutsche Bank nicht grundsätzlich ein Problem. Doch er verändert Aufwand, Risikoprofil und wirtschaftliche Kalkulation. Wer seine Bank- und Depotstruktur erst nach dem Wegzug überprüft, hat möglicherweise genau dann weniger Optionen, wenn er sie am dringendsten braucht.
Read article